Life Insurance Laddering Strategy Explained
Michael Jewell
Oct 06 2026 13:00
Life can change quickly. A new home, a growing family, debt repayment, and long-term planning can all create different financial responsibilities over time. Because those responsibilities do not remain the same forever, your life insurance coverage may need to change as well.
At Michael Jewell Insurance, we help Houston-area families explore life insurance options that fit their goals today while allowing room for the future. One approach worth considering is life insurance laddering, which uses multiple policies with different coverage amounts and term lengths instead of relying on one large policy for every stage of life.
What Is Life Insurance Laddering?
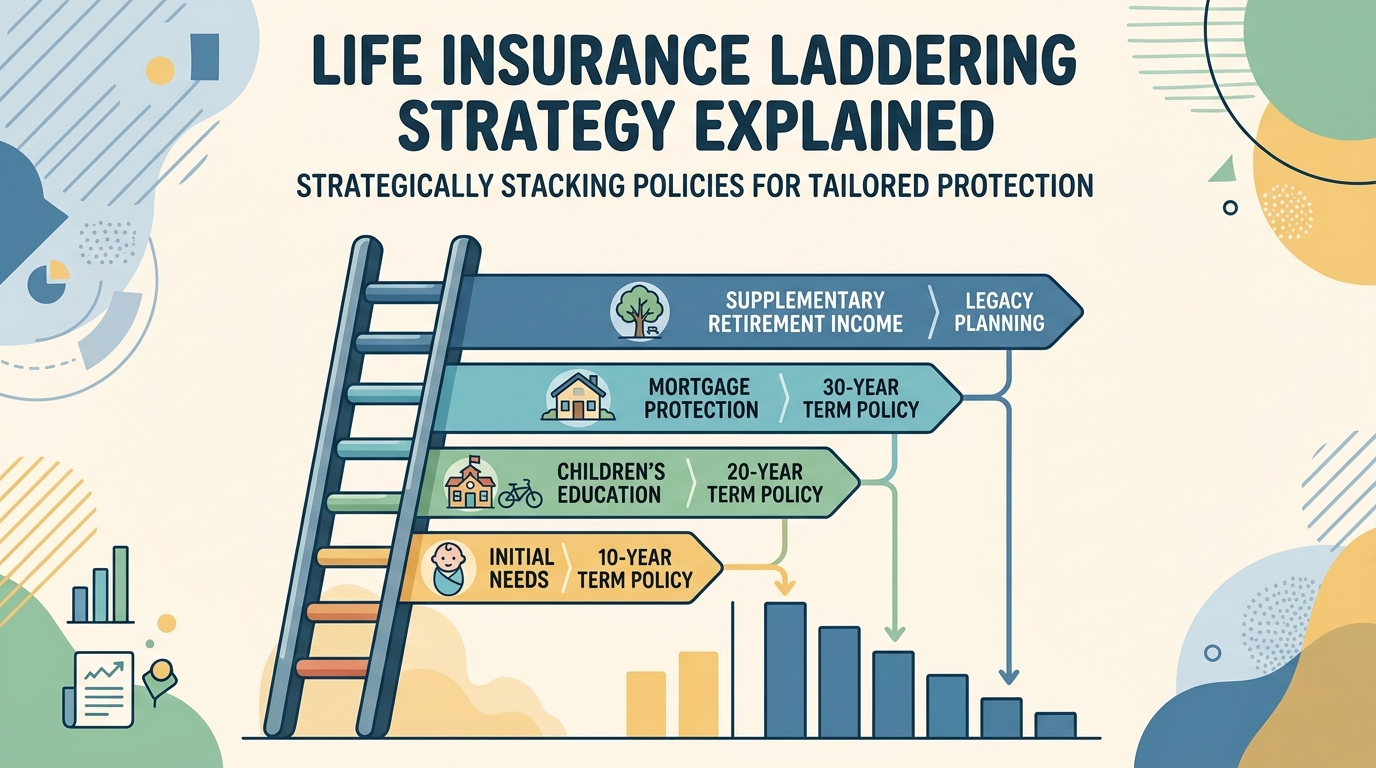
Life insurance laddering means building coverage with more than one policy. Each policy is selected to address a particular financial responsibility, such as temporary debt, a mortgage, or the years when children depend on your income.
Rather than carrying the same large death benefit for decades, a laddered plan is designed to reduce as certain obligations are expected to end. When a specific need goes away, the policy intended to support that need can expire, while other coverage remains in place.
This can create a more tailored life insurance strategy for people whose financial needs are likely to look different over the years.
Aligning Coverage With Life’s Financial Milestones
A key benefit of laddering is the ability to organize life insurance around changing priorities. Early in a career, for example, a person may have student loans or other debt that needs protection. Later, a mortgage and the cost of raising children may become the larger concern.
A shorter-term policy may be used to help account for early debt, while a longer-term policy could help provide protection through the mortgage years and while children are completing their education. This approach allows the amount of coverage to better match the responsibilities you expect to have at different points in life.
Instead of purchasing one policy intended to address every possible future scenario, a ladder can assign coverage to individual obligations. As those obligations decrease, your overall protection can decrease naturally as well.
How a Laddered Plan May Help Manage Costs
Cost is another reason some households consider life insurance laddering. Shorter-term life insurance policies may cost less than coverage designed to last for a longer period. By matching policy durations to specific financial needs, you may avoid paying for a larger amount of protection after that need has ended.
For instance, if a major loan is expected to be paid off within a defined number of years, it may not be necessary to maintain coverage for that loan well beyond its payoff date. With laddering, the policy connected to that debt can end when the obligation does.
Still, this structure is not ideal for every situation. Some people may expect ongoing debt, long-term dependent care, or other responsibilities that will not decline over time. In those cases, reducing coverage through a laddered approach may not reflect their actual needs.
Flexibility When Circumstances Change
Financial plans are rarely permanent. Marriage, children, career changes, property purchases, and other milestones can affect the level and type of insurance protection a household needs.
A life insurance ladder can offer flexibility by allowing several policies to work together. Instead of needing to replace one large policy each time circumstances change, you may be able to adjust your overall strategy around current needs and future expectations.
As an independent insurance agency in Houston, Michael Jewell Insurance can help you consider life insurance alongside the rest of your protection plan. Your life coverage may be part of a broader conversation that includes home insurance in Texas, auto coverage, flood insurance, umbrella protection, or business insurance for Houston-area owners.
Combining Term and Permanent Life Insurance
Many life insurance ladders are built primarily with term policies, but some people also include permanent coverage in their plan. A smaller whole life policy, for example, may address needs that continue beyond temporary obligations.
Depending on the policy, permanent life insurance can provide lifetime coverage, the potential to build cash value, access to funds for retirement or emergencies, and living benefits if a serious illness occurs. These features can serve a different purpose than coverage intended only for a mortgage or short-term debt.
By combining term and permanent policies, some individuals balance more affordable protection for temporary needs with coverage intended to support longer-range goals. Michael Jewell Insurance can help Houston families review the options available and determine how different policy types may work together.
An Example of a Life Insurance Ladder
Consider a 30-year-old with a young family. Their life insurance plan could include several policies, each intended for a separate responsibility:
- A $250,000 policy with a 10-year term to help account for student loans or debt from the early years of a career.
- A $500,000 policy with a 20-year term to help protect a mortgage and provide support while children are growing up and completing school.
- A $250,000 whole life policy intended to help with final expenses and leave a financial legacy.
In this example, every policy has a distinct role. As debts are paid down or other shorter-term obligations come to an end, the related term coverage may no longer be needed. The remaining policies can continue to provide protection for the responsibilities that still exist.
Keeping Options Open for the Future
Life insurance laddering may also provide added choices when individual term policies approach the end of their terms. Many term policies include conversion provisions that may allow some or all of the coverage to be changed to a permanent policy without another medical exam.
That option can be valuable if your health changes later and obtaining new coverage becomes more difficult or costly. Instead of beginning from scratch, you may have a way to adjust protection based on your circumstances at that time.
Your insurance needs may not stay fixed, and having options can bring greater confidence to long-term planning. Whether you are comparing life insurance in Houston, looking for online auto or home insurance quotes, or reviewing insurance for your business, Michael Jewell Insurance is here to make the process more approachable.
Choosing the right life insurance strategy depends on your financial goals, family responsibilities, and plans for the years ahead. Life insurance laddering may be a practical way to align protection with changing needs while preserving flexibility. Contact Michael Jewell Insurance today at (281) 481-2221 to discuss your options and build a plan designed around your goals.